Self-employed? Let's find the best way to qualify your income.
Tax write-offs, business income, 1099s, and variable deposits don't always fit neatly into a traditional mortgage application. We'll help determine the best way to document your income before recommending a loan structure.
- Tax returns aren't always the only way to evaluate self-employed income
- For purchase, refinance, or accessing your home equity
- Declined elsewhere for being self-employed? Worth a second look
- One licensed loan officer who understands self-employed income
Find the best way to qualify your self-employed income
Answer a few quick questions to see which mortgage qualification paths may fit your situation. A licensed Watermark Home Loans loan officer reviews your answers personally.
Takes about 60 seconds • No Social Security number • No hard credit pull
- A few simple questions — no documents, no application
- Your information is used only to review your options
- Reviewed by a licensed Watermark Home Loans loan officer
Built for the way you actually earn
Traditional guidelines weren't designed around business owners. We review the documentation that reflects your real income — then recommend a path.
More than one way to document income
Tax returns, 1099s, a CPA-prepared P&L, or 12–24 months of bank statements — we'll determine which approach best reflects your income.
A human who gets it
A licensed loan officer who understands self-employed income reviews your file — not an algorithm that auto-declines.
Watermark Home Loans
An established lender with in-house processing, underwriting, and closing, licensed to lend in 47 states and DC.
No Paystubs? You May Still Have Mortgage Options
If you're self-employed, you may not receive traditional paystubs like a W-2 employee. Certain mortgage programs can use other ways to document qualifying income, including bank statements, 1099 income, or other eligible documentation.
Bank Statements
Eligible borrowers may be able to use qualifying deposits from personal or business bank statements.
1099 Income
Some programs may allow qualifying income to be documented using 1099 earnings.
Other Income Documentation
Depending on the program and borrower, other eligible documentation may be available instead of traditional paystubs.
Takes about 1–2 minutes. No obligation.
No Tax Returns? You May Still Have Mortgage Options
If you're self-employed, you may not have traditional tax-return income that fits standard mortgage guidelines. Certain programs may allow eligible borrowers to qualify using other documentation, such as bank statements, 1099 income, or asset-based review.
Bank Statement Programs
Eligible self-employed borrowers may be able to qualify using recent personal or business bank statements instead of tax returns.
1099 Income
Some programs may allow qualifying income to be documented using 1099 earnings, depending on your work history and scenario.
Asset-Based Review
Depending on the program and your overall financial picture, other eligible documentation or asset-based approaches may be available.
Takes about 1–2 minutes. No obligation.
Self-employed borrowers shouldn't be judged by one document.
Depending on the scenario, income may be reviewed through tax returns, bank statements, 1099s, a profit & loss statement, or assets. The goal is to determine the best available qualification route for you — not to push one program.
What would you like to do?
Self-employed borrowers can be reviewed across purchase, refinance, and equity scenarios.
Buy a home
Purchase a primary residence, second home, or investment property — with an income review built around how you actually earn.
Refinance
Lower your payment, change your term, or take cash out — even if a traditional refinance turned you down for income documentation.
Access your equity
Pull cash from the equity you've built — for your business, a major expense, or consolidating debt.
Bank Statements to Qualify for a Mortgage
Traditional tax returns are not always the only way to document income. Certain mortgage programs may allow eligible self-employed borrowers to qualify using deposits shown on personal or business bank statements.
Bank Statement Income
Income may be calculated using qualifying deposits from recent personal or business bank statements.
Built for Self-Employed Borrowers
Designed for business owners, independent contractors, freelancers, and other borrowers whose tax returns may not reflect their full cash flow.
Purchase or Refinance
Bank statement programs may be available for both home purchases and refinances depending on the borrower and property.
- 1
Tell us about your situation
Answer a few questions about your income, business, property, and loan goals.
- 2
We review your options
A licensed loan officer reviews which documentation and programs may fit your situation.
- 3
Compare available solutions
Review potential mortgage options and decide whether you want to move forward.
Takes about 1–2 minutes. No obligation.
Several ways self-employed income can be documented
Tax returns aren't always the only way to evaluate self-employed income. Your loan officer will determine which of these best reflects your financial picture.
Tax returns
Traditional qualification still works well for many self-employed borrowers.
Bank statements
12 or 24 months of personal or business statements may be considered.
1099 income
Your 1099s may support qualifying income if you're a contractor or gig earner.
Profit & loss
A CPA-prepared P&L can support your qualifying income.
Your assets
Strong savings or investments but low documented income? Asset depletion may be an option.
This is for you if…
A personalized review helps when your income picture is more complicated than a W-2.
- You're a business owner, 1099 contractor, freelancer, or gig earner
- You write off enough that your tax returns show low income
- A traditional lender declined you for income documentation
- Your business has strong deposits but variable or seasonal income
How it works
A modern process with a real loan officer who works with self-employed borrowers every day.
- 1
Answer a few quick questions
Share your goal, how you earn income, and a few basics about the property.
- 2
We talk through your income
Your loan officer reaches out to learn how your income is structured and determines which qualification approach may make the most sense.
- 3
You review your options
Once there's enough information — which may include reviewing income documentation — you'll get a clear explanation of the loan structures that may fit.
Reviewed by a licensed Watermark Home Loans loan officer who works with self-employed borrowers.
Not an algorithm that auto-declines the moment your tax returns look light. A licensed mortgage professional reviews how you actually earn, explains which qualification paths may fit, and helps you compare your options — then you decide.
Frequently Asked Questions
Common questions from self-employed borrowers.
Not necessarily. Self-employed borrowers may have several ways to document income depending on the loan program and their situation. That can include tax returns, bank statements, 1099 income, or other documentation methods.
Yes, there may still be options. Write-offs can reduce the income shown on tax returns, but some programs may use other ways to evaluate income, such as bank statements or other business documentation.
Yes, some mortgage programs allow self-employed borrowers to qualify using personal or business bank statements instead of traditional tax-return income. The best option depends on how your business is structured and your overall loan scenario.
Yes. 1099 income can often be used to qualify, and in some cases there may be options that are more flexible than traditional tax-return qualification. The right approach depends on your income history and documentation.
No hard credit pull is required to complete the initial questionnaire. You can start by sharing a few basic details about your situation, and any credit review that may be needed later can be discussed before moving forward.
It depends on the best qualification path for you. You may be asked for tax returns, 1099s, personal or business bank statements, profit-and-loss statements, or other income documentation. The goal is to determine which documentation method gives the clearest picture of your income.
Talk With a Loan Officer Who Understands Self-Employed Income
Have questions about bank statements, 1099 income, tax returns, or which mortgage option may fit your situation? Schedule a quick call to review your scenario with a licensed loan officer.
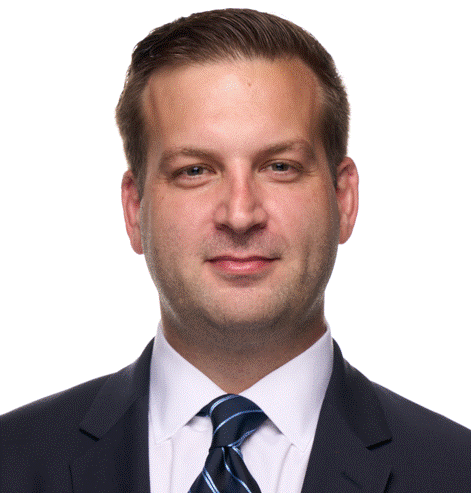
Brian Alterman
Mortgage Loan Officer
NMLS 1295878 | Watermark Home Loans
Choose a time that works for you. No obligation.
See If You Qualify
Answer a few quick questions to see which self-employed mortgage options may fit your situation. No obligation.
Takes about 1–2 minutes. One question at a time.
Ready to get started?
If you already know you want to move forward, you can start the full mortgage application now.